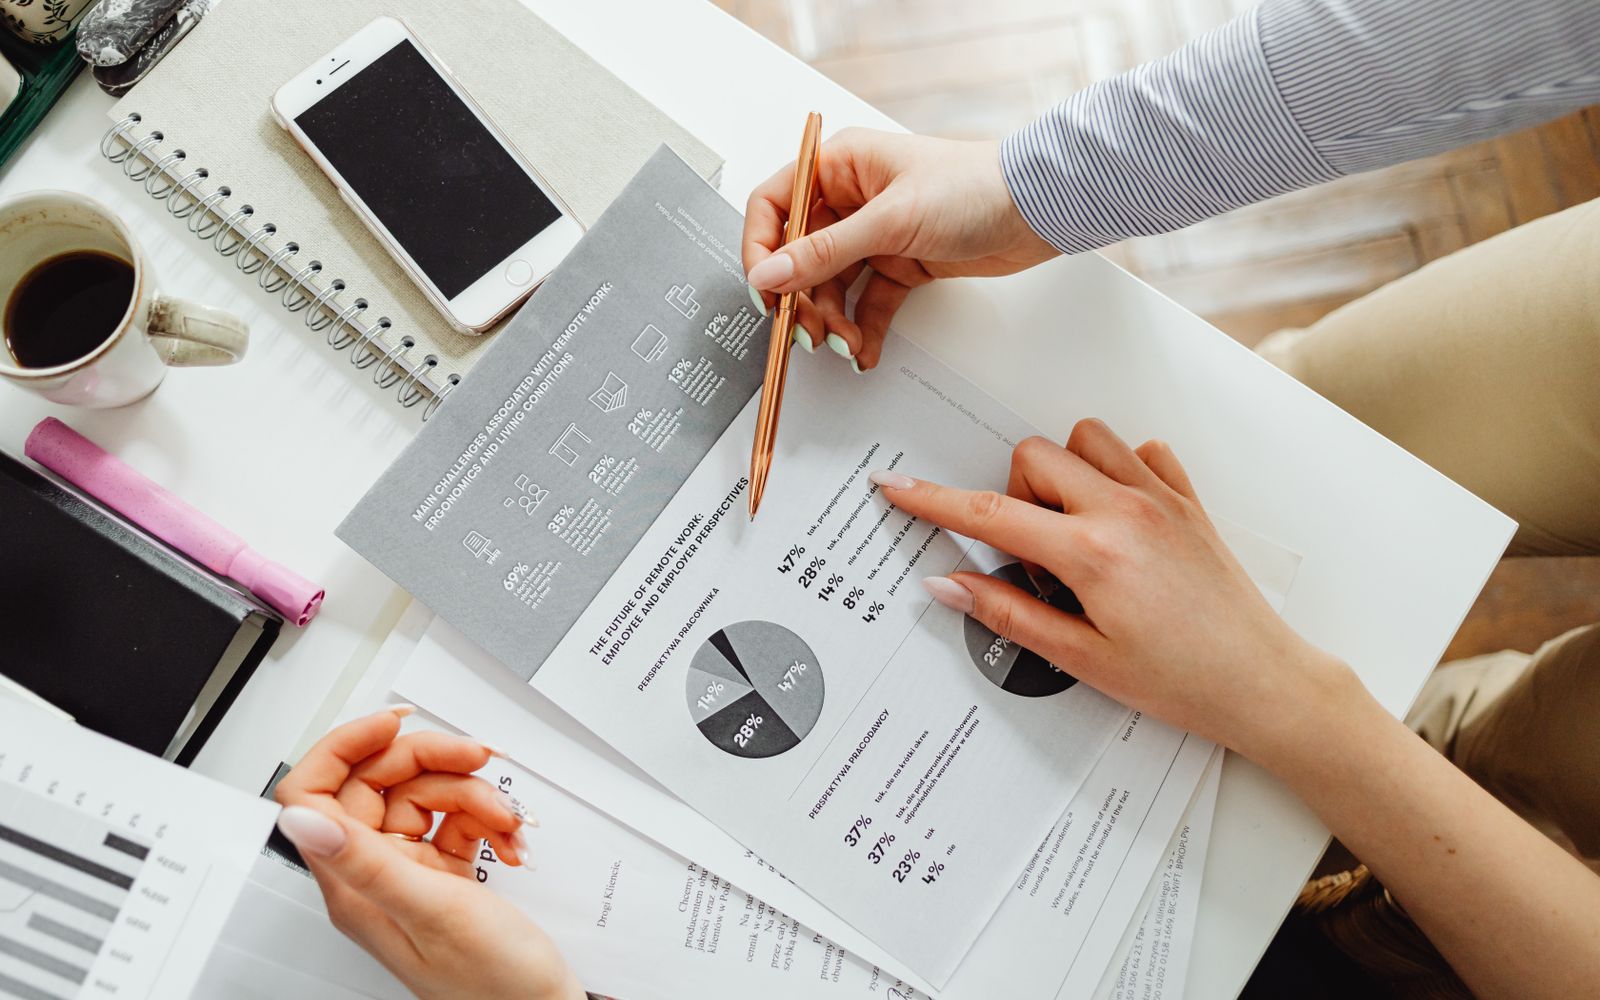
Financial dashboard for photographers in St. Margrethen: the practical guide
Swiss accounting law (art. 957 ff. of the Code of Obligations) sets a precise frame, yet day-to-day practice often stays fuzzy. This guide walks through what actually matters for a business based in St. Margrethen.
The Swiss legal frame for financial dashboard
Swiss accounting law has been unified in the Code of Obligations since 2013: the same bookkeeping rules (art. 957a CO) and retention rules (art. 958f CO — 10 years for books, vouchers and reports) apply regardless of legal form. Financial dashboard sits squarely within this frame, including for companies based in St. Margrethen.
The law also settles the form: accounts may be kept in a national language or in English, on paper or electronically (art. 957a para. 5 CO). That pragmatism lets financial dashboard run entirely on digital tools — no paper binder is required.
Outsource financial dashboard or keep it in-house?
A good test before choosing: ask the fiduciary HOW it wants to receive the documents. A precise answer (formats, frequency, platform) says more than any brochure — including in St. Margrethen.
A business in St. Margrethen can combine the models: internal day-to-day entry, monthly external supervision, closing and taxes with the specialist — financial dashboard splits very well.
Year-end closing: how the mechanics work
Companies exceeding two of three thresholds for two consecutive years — CHF 20 million balance sheet total, CHF 40 million revenue, 250 full-time positions — move to an ordinary audit. Below that, the limited audit applies, and companies with no more than ten full-time positions on annual average can opt out with the consent of all shareholders.
For financial dashboard, a closing checklist reused every year transforms the exercise: same steps, same checks, same documents — only the year changes.
Digitalising financial dashboard: what actually works
Security is part of digitalisation: named access, tested backups, encryption of sensitive data. A digital accounting file is protected like a safe — because it is one.
Migrate in stages: supplier invoices first (high volume, immediate gain), then receivables with the QR-bill, finally payroll and the closing. At each stage, comparing one month before/after is enough to prove the gain — no theoretical promises needed.
St. Margrethen: what changes, what does not
St. Margrethen (postal code 9430, canton St. Gallen) applies the same federal rules as the rest of the country: what changes in St. Margrethen are the cantonal counterparts — tax administration, compensation office, commercial register.
Federal deadlines do not move in St. Margrethen: VAT within 60 days, salary declaration in January, 10-year record retention — postal code 9430 changes nothing about those rules, only the sender's address.
Frequently asked questions
Which documents should be prepared for the year-end closing?
Bank and cash statements at the closing date, the inventory of stock and work in progress, final AHV/LPP/accident settlements, contracts signed or amended during the year, invoices straddling two years and the detail of accruals. With an up-to-date document archive, most of it is already there. The list is identical in St. Margrethen: the CO dictates it, not the commune.
When must a business register for VAT?
As soon as its worldwide annual turnover reaches CHF 100,000 (CHF 250,000 for non-profit sports or cultural associations). Below that, voluntary registration remains possible and often makes sense to reclaim input VAT on investments. The threshold is federal: it applies in St. Margrethen as everywhere in Switzerland.
What are the current Swiss VAT rates?
Since 1 January 2024: 8.1% (standard), 2.6% (reduced — for example food and medicines) and 3.8% (accommodation). Returns must be filed and paid within 60 days after the period ends (quarterly under the effective method, semi-annually under the net tax rate method). These federal rates apply unchanged in St. Margrethen.
What is the difference between a limited and an ordinary audit?
The ordinary audit applies to companies exceeding, for two consecutive years, two of three thresholds: CHF 20 million balance sheet total, CHF 40 million revenue, 250 full-time positions. Others fall under the limited audit, and those with no more than ten full-time positions on annual average can opt out with all shareholders' consent. These federal thresholds do not depend on the registered seat — in St. Margrethen as anywhere.
Also worth reading
In neighbouring municipalities
Switch to accounting that keeps itself up to date
MyFiducia.ai automates financial dashboard for businesses in St. Margrethen: AI-read documents, posting suggestions, VAT and exports ready for your fiduciary. Try the platform or browse our other guides.
The application is operated in French.